
Legal Compliance for Businesses A Beginner Friendly Guide to Staying on Track

A business can have a strong product, happy customers, and healthy sales, yet still run into trouble if it misses a licence renewal, ignores tax rules, or handles employee records poorly. Compliance may sound like paperwork, but it is really about keeping the business safe, trusted, and ready to grow.
For beginners, the subject can feel wide. There are registrations, tax filings, contracts, labour laws, data rules, industry licences, and record-keeping duties. The good news is that compliance becomes much easier when it is broken into clear steps and built into everyday operations.
This guide explains the basics of legal compliance for businesses, why it matters, and how to start building good habits without feeling overwhelmed.
This article is for general information only and is not legal advice. For decisions that affect your business, speak with a qualified professional.

Legal compliance means following the rules that apply to your business
Legal compliance means meeting the laws, regulations, standards, and official requirements that apply to how a business operates. These rules can come from central laws, state laws, local authorities, regulators, tax departments, and industry-specific bodies.
For example, a food business may need food safety registration or licensing. A company that hires employees must follow wage, leave, workplace safety, and anti-harassment requirements. A business selling goods or services may need GST registration if it crosses the relevant threshold or falls under a category where registration is required.
Compliance does not mean knowing every law in detail. It means knowing which rules apply, assigning responsibility, keeping records, and taking action on time.
The main areas most businesses should understand
While every business is different, beginners can start with these broad categories.
Business structure and registration
The first compliance step is choosing and registering the right structure. Common options in India include sole proprietorship, partnership, limited liability partnership, and private limited company. Each structure has different rules for ownership, liability, taxes, filings, and closure.
A private limited company, for instance, has more formal compliance duties than a sole proprietorship. It may need board records, annual filings, statutory registers, and auditor-related processes. A sole proprietorship may be simpler, but the owner may carry unlimited personal liability.
Tax compliance
Tax compliance covers income tax, GST, TDS, professional tax where applicable, and other tax obligations linked to the business model. This includes timely registration, correct invoicing, tax collection, tax payment, return filing, and keeping supporting documents.
A common mistake is treating tax only as an annual task. In practice, tax compliance often has monthly, quarterly, and annual actions.
Licences and permits
Many businesses need licences based on activity and location. Examples may include Shops and Establishments registration, FSSAI registration or licence, trade licence, import-export code, pollution consent, factory licence, or sector-specific permissions.
A small design studio and a packaged food manufacturer will not have the same compliance list. The key is to identify requirements before starting operations, not after a notice arrives.
Employment and labour laws
Once a business hires people, compliance expands. It may include employment contracts, wage records, leave policies, working hours, workplace safety, provident fund, employee state insurance, gratuity, maternity benefits, and rules on prevention of sexual harassment at the workplace.
Some laws apply only after employee count or wage thresholds are crossed. Businesses should track these thresholds as they grow.
Contracts and customer protection
Contracts help prevent disputes. They set out payment terms, delivery timelines, responsibilities, confidentiality, refund rules, dispute resolution, and termination rights.
Businesses also need fair customer practices. Misleading claims, unclear pricing, poor refund handling, or unsafe products can create legal and reputational risk.
Data protection and privacy
Businesses collect names, phone numbers, addresses, payment details, employee records, and customer preferences. This data must be collected, stored, used, and shared responsibly.
India’s data protection framework places growing focus on consent, purpose, security, and accountability. Even small businesses should avoid collecting more data than they need and should limit access to sensitive information.
Compliance supports growth rather than slowing it down
Many beginners see compliance as an expense. That view changes when a business faces a penalty, a blocked payment, a failed due diligence review, or a dispute that could have been avoided.
Good compliance protects the business in several ways.
It reduces legal and financial risk
Missed filings, expired licences, incorrect invoices, unpaid statutory dues, or weak employee records can lead to penalties and disputes. Some issues can also affect bank accounts, vendor relationships, or the ability to bid for work.
A business that keeps its records current can respond faster to notices, audits, or customer questions.
It builds trust with customers and partners
Customers want to know that a business is reliable. Vendors want payment clarity. Larger companies often check registrations, tax status, licences, and contracts before signing agreements.
Compliance gives others confidence that the business is serious and stable.
It makes funding and expansion easier
Banks, investors, franchise partners, and large buyers often review compliance before moving ahead. They may ask for tax returns, incorporation documents, GST records, licences, employment records, and contract copies.
A business that keeps these ready avoids last-minute panic.
It helps founders make better decisions
Clean records reveal useful facts. Tax reports show revenue patterns. Payroll records show hiring costs. Contract records show payment delays. Compliance data can help owners plan instead of relying only on memory.

Beginners can start with a simple compliance system
Compliance becomes manageable when it has a system. The system does not need to be expensive. It only needs to be clear, consistent, and reviewed often.
Identify what applies to the business
Start by mapping the business.
Ask simple questions:
What is the legal structure?
What products or services are sold?
Where does the business operate?
Does it sell online, offline, or both?
Does it hire employees, consultants, or contractors?
Does it collect customer data?
Does it import, export, manufacture, store food, handle waste, or use regulated materials?
Does it operate from a shop, home, factory, warehouse, or shared space?
These answers help create the first compliance list. A chartered accountant, company secretary, lawyer, or industry consultant can help confirm it.
Create a compliance calendar
A compliance calendar lists all recurring due dates. This may include GST returns, TDS payments and returns, income tax advance tax, licence renewals, annual filings, employee-related payments, insurance renewals, and contract review dates.
Use a spreadsheet, accounting software, calendar app, or a simple register. The tool matters less than the habit.
A good calendar should include:
The task name
The due date
The person responsible
The documents needed
The current status
Proof of completion
Set reminders before the due date. Waiting until the final day creates stress and increases mistakes.
Keep documents in one place
Missing documents make compliance harder. Store scanned and physical copies of important records in organised folders.
Key documents often include:
Registration certificates
PAN and TAN records
GST documents
Licences and permits
Rent or ownership documents
Invoices and receipts
Bank statements
Tax returns and challans
Employee records
Contracts and purchase orders
Insurance policies
Board or partner decisions, where applicable
Use clear file names. For example, `GST_Return_April_2026.pdf` is easier to find than `scan123.pdf`.
Use written agreements
Verbal understandings are risky. Use written agreements with customers, vendors, employees, freelancers, landlords, and partners.
A basic agreement should cover:
Scope of work or goods
Price and payment timeline
Delivery responsibilities
Confidentiality
Ownership of work or materials
Cancellation or termination
Dispute handling
Applicable taxes
Templates can help, but they should be reviewed for the actual business situation. A copied contract may miss key risks.
Separate personal and business finances
Mixing personal and business money creates confusion. It makes tax work harder and weakens financial records.
Open a dedicated business bank account where possible. Use it for income, expenses, salaries, taxes, and vendor payments. Keep bills and receipts linked to each transaction.
This habit also helps during loan applications, audits, and internal reviews.
Review compliance when the business changes
Compliance is not a one-time setup. A change in business activity can trigger new rules.
Review compliance when:
Revenue grows sharply
Employee count increases
A new branch opens
The business starts selling in another state
A new product category is added
The business starts manufacturing
Customer data collection increases
Foreign clients or suppliers are involved
Ownership changes
Growth is good, but it often brings fresh obligations.
Common compliance challenges have practical solutions
Most compliance problems do not start with bad intent. They often come from confusion, delay, unclear responsibility, or poor record-keeping.
The rules feel too complex
Legal language can be difficult. Different authorities may use different terms. Requirements also vary by state and sector.
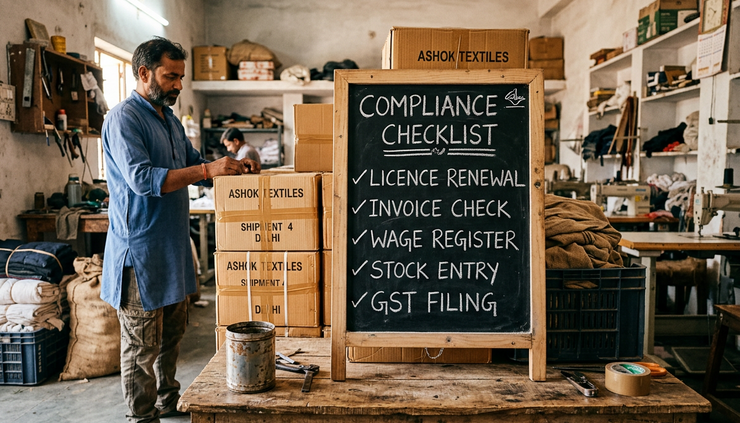
The fix is to translate rules into a plain checklist. Instead of writing “statutory filing obligations,” write the exact task, such as “file monthly GST return” or “renew trade licence before expiry.”
Professional help is useful here. Ask experts to explain what must be done, why it matters, and how often it must be repeated.
No one owns the task
In small businesses, everyone is busy. Compliance tasks can fall between the owner, accountant, HR person, and operations team.
Assign each task to a named person. If an outside professional handles filing, someone inside the business should still track the due date and collect records.
Responsibility should never be vague.
Records are scattered
Invoices may sit in WhatsApp chats, receipts in drawers, contracts in email, and licence copies with one employee. This creates problems during filing or audits.
Set one rule. Every important document must be saved in the agreed folder or register within a fixed time. For example, all vendor invoices are uploaded every Friday.
Small routines prevent large clean-up work later.
The business reacts only after notices arrive
A notice from a department should never be ignored. Delayed responses can make a manageable issue worse.
Create a process for notices:
Record the date received
Read the subject carefully
Share it with the right adviser
Collect supporting documents
Respond within the stated time
Keep proof of submission
If the notice is unclear, get help early.
Costs feel hard to manage
Professional fees, software, registrations, and renewals may feel like a burden for a new business. Yet non-compliance can cost far more.
Start with the essentials. Pay for expert advice at key points, such as setup, tax planning, hiring, contracts, and expansion. Use simple tools for tracking. As the business grows, move to better systems.
Laws change over time
Rules can change through amendments, notifications, court decisions, or policy updates. A checklist made two years ago may no longer be enough.
Schedule a basic compliance review at least once a year. Also speak to advisers when the business enters a new activity or location.
A beginner-friendly compliance checklist can guide the first month
For a new or growing business, the first month is a good time to build the foundation.
Use this starter plan.
Week | Focus area | What to do |
Week 1 | Business identity | Confirm structure, registrations, PAN, bank account, and basic records |
Week 2 | Taxes and invoices | Check GST, TDS, invoicing format, receipt storage, and accounting process |
Week 3 | Licences and contracts | List activity-based licences, review vendor and customer agreements |
Week 4 | People and data | Set up employee records, policies, payroll basics, and data handling rules |
This checklist is only a start. The actual list depends on the business type, size, state, and sector.
Good compliance habits are easier than emergency fixes
Compliance works best when it becomes part of routine business life. It should not live only in the accountant’s inbox or the founder’s memory.
Build these habits early:
Check the compliance calendar every week
Save documents as soon as they are created
Use written contracts for important dealings
Review licences before they expire
Keep employee and payroll records current
Track thresholds for tax and labour laws
Ask for advice before launching a new activity
Respond to official notices quickly
A simple rule helps: if a decision affects money, people, customers, data, licences, or ownership, check whether it has a compliance impact.

Staying compliant keeps the business ready for what comes next
Legal compliance is not just about avoiding penalties. It helps a business earn trust, protect its people, manage money better, and grow with fewer surprises.
Beginners do not need to master every law at once. Start with the basics. Know the rules that apply, keep records clean, track dates, write things down, and ask for help before small gaps become expensive problems.
The best time to build a compliance system is at the start. The next best time is now.
Comments